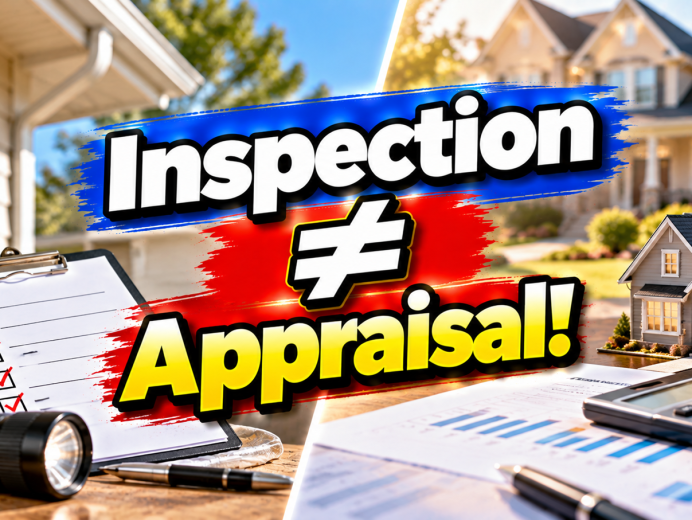
The home inspection vs appraisal Central Jersey question comes up on almost every first-time buyer call I take, usually phrased as “wait, didn’t we already have someone look at the house?” Both happen in the weeks after your offer is accepted on a home in Edison, Metuchen, or East Brunswick, both involve a stranger walking through the property with a clipboard, and both can change the deal. But one is about the home’s condition and protects you, and the other is about the home’s value and protects your lender. Understanding the five differences below is the difference between a buyer who reads both reports with confidence and one who panics at the wrong one.
Quick summary
- Inspection = condition. You hire the inspector, you get the report, and you use it to negotiate repairs or credits or to walk away within your contract’s inspection period.
- Appraisal = value. Your lender orders it, you usually pay for it, and the number decides how much the bank will lend.
- A house can pass inspection and still appraise low, or appraise fine and have a cracked heat exchanger. The two reports answer different questions.
- When a Central Jersey home appraises below the contract price, your options are a price reduction, covering the gap in cash, a reconsideration of value, or walking away if your contract allows it.
Table of contents
What the Home Inspection Does
A home inspection is a visual, non-invasive evaluation of the property’s condition, performed by an inspector licensed by the New Jersey Division of Consumer Affairs. The inspector checks the roof, exterior, structure, attic, basement, electrical, plumbing, heating and cooling, and interior safety items, then writes a report listing defects, safety concerns, and components near the end of their service life. You choose the inspector, you pay for it directly, and the report belongs to you.
The inspection exists to answer one question: what will this house cost me to own and what needs attention now? It is the basis for the repair request your attorney sends the seller, and in New Jersey it is tied to a contingency that lets you negotiate or cancel over material issues. If you are buying this fall, my post on 7 things to check before you fall in love with a house covers what to look for before you even get to the inspection stage.
What the Appraisal Does
An appraisal is a licensed appraiser’s written opinion of the home’s market value, ordered by your lender to confirm the property is worth enough to secure the loan. The appraiser visits the home, measures it, notes its condition and features, and compares it to recent sales of similar homes nearby, the “comps.” The result is a single number. If that number is at or above your contract price, the loan proceeds as planned. If it is below, the lender will only base the mortgage on the appraised value, and the difference becomes your problem to solve.
The appraisal protects the lender, but under federal rules it also informs you. The Consumer Financial Protection Bureau explains that borrowers on a first-lien mortgage are entitled to a free copy of the appraisal, delivered promptly after it is completed and no later than three business days before closing. Read it. It tells you which comps the appraiser chose and how they adjusted for differences, which is exactly what you need if you decide to challenge the number.
One more thing worth knowing: the appraisal report format is changing. Conventional loans are moving to a more structured, data-driven report that documents the home’s condition and updates in far more detail than before, which I covered in what the new appraisal rules mean for Central Jersey buyers and sellers.
Home Inspection vs Appraisal in Central Jersey: The 5 Differences
| Difference | Home inspection | Appraisal |
|---|---|---|
| 1. Purpose | Condition: what is wrong, unsafe, or aging | Value: what the home is worth based on comparable sales |
| 2. Who orders and who it protects | You choose the inspector; the report is yours and protects you | Lender orders it through an independent process; protects the lender, though you get a copy |
| 3. Required? | Optional by law, strongly recommended, and tied to your contract contingency | Required by nearly every lender for a mortgage; cash buyers can skip it |
| 4. What it produces | A multi-page report of defects, photos, and recommendations | A single value figure with supporting comps and adjustments |
| 5. What happens if it goes badly | Repair request, credit, price reduction, or cancellation within the inspection period | Appraisal gap: renegotiate price, pay the difference in cash, request reconsideration, or cancel if your contract allows |
The most important thing the table shows is that the two reports are independent. A split-level in Piscataway can get a clean inspection and still appraise below contract because three similar homes on the next street sold for less last quarter. A Colonial in Metuchen can appraise above contract in a competitive bidding situation and still have an original electrical panel the inspector flags as a safety concern. Reading one report does not tell you anything about the other.
Where Each One Falls in a New Jersey Purchase Timeline
New Jersey’s sequence is specific, and knowing it helps you plan. After the seller accepts your offer, both sides go through attorney review. When attorney review concludes, your inspection period starts; the number of days is set in your contract. Your inspection, and any add-ons like radon or a sewer camera, happen in that window, and your attorney sends the repair request based on the results.
The appraisal is ordered by your lender around the same time or shortly after, once your loan file is moving. It typically takes one to two weeks from order to report, which means the appraisal result often arrives after you have already resolved the inspection negotiation. That ordering matters: if you negotiated a credit for repairs during the inspection phase and then the home appraises low, you are now solving two separate problems with the same seller, and your mortgage contingency, not your inspection contingency, is what governs the second one.
Key takeaway: the inspection contingency and the mortgage (or appraisal) contingency are two different clauses in your contract. Know the deadline on each one, because missing one can mean losing the protection it gives you.
What to Do When a Central Jersey Home Appraises Low
Appraisal gaps are a real feature of our market when buyers compete and prices move faster than closed comps. When the number comes in under contract, there are four paths, and the right one depends on how much you want the house and how much cash you have.
Ask the seller to reduce the price. Sellers will sometimes meet you at the appraised value, especially if they have no backup offers and the comps are credible. Your Realtor’s job here is to show the seller the appraisal and explain that any financed buyer will hit the same wall.
Cover the gap in cash. If you have the funds, you can pay the difference between the appraised value and the contract price out of pocket. In competitive situations, buyers sometimes offer this up front as an appraisal-gap guarantee to strengthen their offer; what makes a strong offer beyond price includes exactly this kind of term.
Request a reconsideration of value. If the appraiser missed a better comp or made an error, your lender can submit a reconsideration request with supporting sales data. These succeed sometimes, not always, and they take time, so start immediately.
Walk away. If your contract has a mortgage contingency and the lender will not approve the loan at the needed amount, you may be able to cancel and recover your deposit. Your attorney reads this clause, not you, so call them the day the appraisal arrives.
Sellers face the mirror image of this, and the best protection on their side is preparation, which is why I wrote the pre-listing inspection guide for Central Jersey sellers.
Home Inspection vs Appraisal Central Jersey FAQ
Do I need both a home inspection and an appraisal when buying in Central Jersey?
If you are financing, the appraisal is required by your lender. The inspection is your choice, but it is the only one of the two that tells you about the home’s condition, and skipping it means giving up your inspection contingency.
Can a house pass inspection but appraise low?
Yes, and it happens regularly in competitive Central Jersey markets. The inspection evaluates condition; the appraisal evaluates value against recent comparable sales. A well-maintained home can still appraise below a contract price that outran the comps.
Who pays for the appraisal and the inspection?
The buyer typically pays for both. The inspection is paid directly to the inspector you hire. The appraisal fee is usually collected by your lender, since the lender orders it, and it often appears on your loan estimate.
Does the appraiser check for problems like the inspector does?
Only at a surface level. An appraiser notes overall condition and obvious issues that affect value or lender requirements, but does not test systems, enter attics the way an inspector does, or produce a defect list. Never treat an appraisal as a substitute for an inspection.
Which one comes first, the inspection or the appraisal?
In New Jersey, the inspection usually happens first, during the inspection period that begins after attorney review. The appraisal is ordered by the lender around the same time and often arrives a week or two later.
An inspection tells you what the house is. An appraisal tells you what the house is worth to a lender. Central Jersey buyers who keep those two questions separate, read both reports, and know the deadline on each contingency rarely get surprised between contract and closing. The buyers who get surprised are usually the ones who assumed one report covered both.
Under contract, or about to make an offer in Central Jersey?
I’ll walk you through what to expect at the inspection, how the appraisal is likely to come in based on current comps for that street, and how to write the contingencies so you are protected on both.
Jasmine Tsui (徐佳美)
Weichert, Realtors® | NJ Realtors® Circle of Excellence Platinum | Top 1% companywide
Central Jersey Realtor and Chinese-speaking real estate agent with 16+ years in real estate, 200+ closed transactions, 220+ five-star reviews
📍 123 Lincoln Hwy, North Edison, NJ 08820
📞 201-920-5825 · 🌐 NextMoveNJ.com
Serving Edison, Metuchen, East Brunswick, South Brunswick, Piscataway and surrounding Middlesex County · Fluent in English, Mandarin (国语) and Cantonese (粤语)
NJ Real Estate License #2075070 · Equal Housing Opportunity
This article is general information for Central Jersey home buyers and is not legal or lending advice. Contingency terms, appraisal delivery rules, and lender requirements vary; confirm current terms with your attorney and your loan officer. Weichert, Realtors® · Equal Housing Opportunity.