The mortgage protection insurance NJ letters usually start arriving about a week after you get your keys. A client who closed on a Colonial in North Edison this fall texted me photos of seven of them in the first ten days. Two had her lender’s name printed across the top. One said “Final Notice.” Another came in a window envelope that looked like a county tax bill. Her question was the one I hear after almost every closing in Edison, Metuchen, and East Brunswick: “Is this something I was supposed to buy? Did I miss a step?”
The short answer is no. The longer answer, which is what this article is about, is that the letters are advertising, the product they are selling is real but optional, and the better question is not “should I buy this?” but “what kind of protection does my family actually need now that we own a home, and who should I talk to about it?”
Quick summary
- Mortgage protection insurance (MPI) letters are third-party marketing, not a requirement from your lender, your attorney, or any government office. The sender found you through the public mortgage record filed at the Middlesex County Clerk.
- MPI is not PMI. Private mortgage insurance protects the lender and is required on many loans with less than 20% down. MPI is an optional life insurance product you choose to buy or skip.
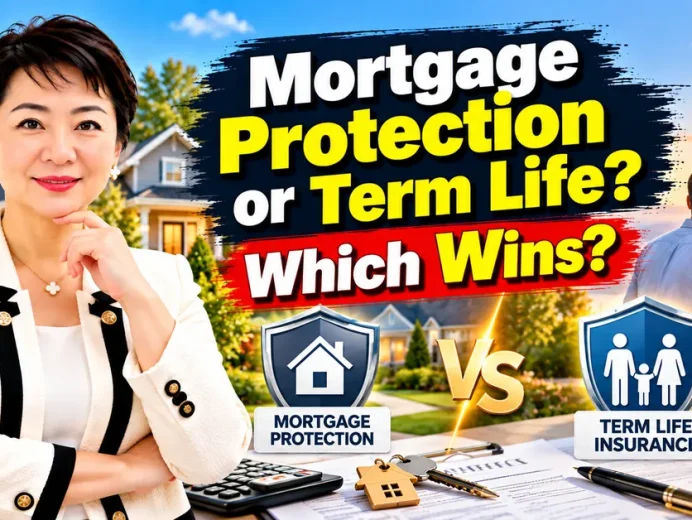
- MPI and term life insurance can cover the same risk, your death during the loan, but they are built differently: who gets paid, whether the benefit shrinks, and how much health underwriting is involved.
- Neither is automatically “better.” The right fit depends on your health, your budget, the coverage you already have through work or elsewhere, and whether you want the payout to go to the bank or to your family.
- Before you respond to any letter, read the five questions below and talk to an appropriately licensed insurance professional about your own situation.
Table of contents
- Why mortgage protection insurance NJ letters show up after closing
- What mortgage protection insurance actually is (and is not)
- Mortgage protection insurance vs term life: the real differences
- Side-by-side: how the two products are built
- Is mortgage protection insurance worth it? 5 questions to ask first
- What to do with the stack of letters
- Mortgage protection insurance NJ: FAQ
Why Mortgage Protection Insurance NJ Letters Show Up After Closing
When you close on a home in New Jersey, your attorney records the deed and the mortgage with the county clerk. In Middlesex County that filing is a public record, and it contains your name, your new address, the name of your lender, and the original loan amount. Marketing companies pull those records every week, sometimes every day, and sell the lists to insurance agencies, home-warranty sellers, biweekly-payment services, and “deed retrieval” outfits. That is how a company you have never heard of knows which bank holds your mortgage and roughly how much you borrowed.
The letters are designed to be opened. The most common tricks I see in my clients’ mail: the lender’s name in large type with a small-print disclaimer that the sender is not affiliated with it; a reference number or “case ID” that sounds like a loan number; deadlines such as “respond within 5 days”; and return addresses that sound governmental. If you look closely there is almost always a line, often in gray text at the bottom, that says the mailing is a solicitation for insurance and that the sender is not your lender. New Jersey’s Department of Banking and Insurance regulates insurance advertising in the state, and a solicitation that is genuinely misleading can be reported there.
None of this means every company sending these letters is dishonest. Some are licensed agencies selling a legitimate product. But the letter’s urgency is manufactured. Nothing about your mortgage changes if you throw it away, and your lender has no idea it was sent. I covered the rest of the post-closing paper trail, including the deed and the first tax bill, in my guide for Edison and Central Jersey buyers deciding whether to buy now; this article focuses on the insurance piece alone.
Key takeaway: a letter that knows your lender and loan amount is not proof of a relationship with your lender. That information is public the day your deed is recorded.
What Mortgage Protection Insurance Actually Is (and Is Not)
Mortgage protection insurance, sometimes called mortgage life insurance or mortgage payment protection, is a form of life insurance built around one debt. If the insured homeowner dies while the policy is in force, the policy pays a benefit intended to cover the remaining mortgage balance. Some versions add riders for disability or job loss that make payments for a limited time. The details vary widely from one policy to the next, which is exactly why reading the actual policy matters more than reading the letter.
Three things MPI is not, because buyers mix them up constantly:
- It is not private mortgage insurance (PMI). PMI is required by most lenders when a conventional loan has less than 20% down, it protects the lender if you default, and it is already built into your monthly payment. The Consumer Financial Protection Bureau explains it plainly at What is private mortgage insurance? MPI, by contrast, protects your household, is optional, and is a separate purchase.
- It is not homeowners insurance. Your lender did require a homeowners policy before closing. That covers the structure and your liability, not your life.
- It is not required by anyone. No New Jersey lender, no attorney, and no township conditions your loan on buying MPI. Every insurance requirement a lender has must be disclosed before closing, and MPI is never on that list.
So the product is legitimate, the need it addresses is real for many families, and the pressure to buy it from a cold letter is entirely artificial. Keep those three ideas separate and the decision gets much clearer.
Mortgage Protection Insurance vs Term Life: The Real Differences
Here is where the conversation usually gets useful. The risk both products address is the same: a wage earner dies and the family is left with a mortgage payment it may not be able to carry. A term life insurance policy covers that risk too. The question is how each product is structured, because the structure decides who controls the money and how the coverage behaves over time.
Who receives the benefit
Many MPI policies are written so the benefit goes toward paying off the mortgage, either paid to the lender directly or earmarked for the loan. A term life policy pays a named beneficiary, usually a spouse, who then decides what to do with the money. Paying off the house might be the right call. It might not: a surviving spouse with a fixed-rate loan and a comfortable payment may prefer to keep the mortgage, keep the cash liquid, and cover tuition, income replacement, or a move closer to family. The difference is flexibility, and it matters more than most buyers realize until they picture the actual scenario.
Whether the benefit shrinks
Because MPI is tied to a debt that goes down over time, many MPI policies have a decreasing benefit that tracks the amortizing balance, while the premium stays the same. Traditional term life has a level death benefit for the length of the term. Some MPI policies are level too, so this is a question to ask about the specific policy in front of you, not an assumption to make from the brochure.
How much the insurer asks about your health
MPI is often marketed as having simplified or no medical underwriting, which is part of its appeal in a mailer: fill out a short form, no exam. Traditional term life typically involves health questions and often a medical exam or a records review. Less underwriting is a genuine advantage for someone who has had trouble qualifying for coverage elsewhere. For a healthy applicant, full underwriting is simply the normal path and is not a drawback. This is the single biggest factor in which product fits a given household, and it is personal, which is why no article can answer it for you.
What happens if you refinance or move
A policy tied to one specific loan may need to be reviewed, adjusted, or replaced when that loan is paid off through a refinance or a sale. A term life policy is tied to you, not to the house at 123 Anywhere Street, and comes with you to the next home. With rates where they have been, a lot of Central Jersey buyers plan to refinance within a few years, so ask how the policy you are considering handles that.
Side-by-Side: How the Two Products Are Built
| Feature | Mortgage protection insurance (typical) | Term life insurance (typical) |
|---|---|---|
| Purpose | Cover the remaining mortgage balance | Replace income and cover any family need, mortgage included |
| Who gets paid | Often the lender, or the benefit is earmarked for the loan | The beneficiary you name |
| Benefit over time | Frequently decreases with the loan balance; some policies are level | Level for the full term |
| Health underwriting | Often simplified or minimal | Usually health questions, often an exam or records review |
| Tied to | A specific loan; review needed on refinance or sale | You; moves with you to the next home |
| Optional riders | Sometimes disability or job-loss payment riders for a limited period | Varies by carrier; living-benefit and other riders may be available |
| Required by lender? | No | No |
| How it is usually sold | Direct mail after a mortgage is recorded | Through a licensed agent or broker after a needs conversation |
Notice what the table does not say: that one costs less, or that one is “better.” Pricing depends on your age, health, the coverage amount, and the term, and a responsible comparison means getting actual quotes for your situation from a licensed professional, not reading a national average. What the table does tell you is which features to ask about.
Is Mortgage Protection Insurance Worth It? 5 Questions to Ask First
I hold a New Jersey insurance producer license alongside my real estate license, and this is the framework I walk through with my own buyers after closing. It is not a recommendation for or against any product. It is the set of questions that gets you to a sensible answer.
1. What coverage do I already have?
Many Central Jersey households have group life insurance through an employer, sometimes one or two times salary, and some already own an individual policy. Add it up before you add to it. Then ask the harder question: is the group coverage portable if you change jobs, and is it enough on its own to carry a Middlesex County mortgage plus property taxes for the years your family would need it?
2. Do I want the money to go to the bank or to my family?
This is the question that separates the two products most cleanly. If you specifically want the house paid off and nothing else, a mortgage-linked product does exactly that. If you want your spouse to have options, a benefit paid to a beneficiary gives them the choice. Think about your own household, not the letter’s headline.
3. Would I qualify for traditionally underwritten coverage?
If you are in good health, you have the full menu available and should see it. If you have a health history that has made coverage hard to get, a simplified-issue product may be the realistic path to protecting the house, and that is a perfectly good reason to consider it. Either way, the answer should come from a licensed professional who has asked about your situation, not from a form on a mailer.
4. How long do I need the coverage, and will it change?
Match the term to the risk. A 30-year loan does not automatically mean a 30-year need; your children will be independent sooner than that, and your balance will fall. Also ask what happens if you refinance or sell in three years, which in the Edison and Metuchen market is common.
5. Who is actually selling this, and are they licensed in New Jersey?
Any person or agency selling insurance to a New Jersey resident must hold a New Jersey producer license, and you can verify it through the Department of Banking and Insurance. Ask for the agent’s name and license number before you give yours. A legitimate agent will not hesitate. A “processing center” with no named agent is a reason to stop.
Key takeaway: “Is mortgage protection insurance worth it?” has no universal answer. “Is my family protected if something happens to me, and is the coverage structured the way I want?” always does.
What to Do With the Stack of Letters
Practically speaking, here is what I tell clients in the first month after closing:
- Do not call the number on the letter to “confirm” anything. Your lender’s number is on your closing disclosure and your first statement. If you are unsure whether a mailing is from them, call that number instead.
- Do not pay for a copy of your deed. The recorded deed comes from your attorney or the county clerk, and certified copies cost a few dollars at the clerk’s office, not the amount some mailers ask for.
- Expect the home warranty, biweekly payment, and “rate reduction” letters too. Same source, same playbook. Biweekly payment services charge a fee to do something most servicers let you do yourself for free by paying extra principal.
- Snap a photo and send it to someone you trust. Your real estate agent, your attorney, or your loan officer has seen hundreds of these and can tell you in a minute whether it is routine marketing.
- Treat the letter as a reminder, not an offer. New homeowners genuinely should review their life insurance after closing, because a mortgage is usually the largest obligation a family takes on. Use the letter as the nudge to have that review with a licensed professional on your terms.
The volume tapers off after two or three months as the lists age. If it does not, the Federal Trade Commission’s prescreened-offer opt-out and the Direct Marketing Association’s mail preference service both cut down on it. And if you believe a specific mailing crossed from aggressive into deceptive, the New Jersey Department of Banking and Insurance accepts consumer complaints about insurance advertising.
中文服务:刚过户就收到一堆“房贷保障保险”信件,不知道该不该理?我同时持有新泽西房地产和保险执照,可以用国语或粤语帮你把这些信件和家庭保障的问题讲清楚。更多中文内容请访问 HomeRunNJ.com。
Prefer to read this in Chinese? My sister site HomeRunNJ.com covers home buying and family financial protection in Mandarin and Cantonese.
Mortgage Protection Insurance NJ: FAQ
Why am I getting mortgage protection letters after buying a house in New Jersey?
Because your mortgage was recorded with the county clerk and is a public record. Marketing companies pull new mortgage filings, which include your name, address, lender, and loan amount, and sell the lists to insurance agencies and other vendors. The letters are advertising, not a notice from your lender.
Is mortgage protection insurance required in NJ?
No. No New Jersey lender, attorney, or municipality requires mortgage protection insurance. Lenders can require homeowners insurance and, on many loans with less than 20% down, private mortgage insurance (PMI), but those are disclosed before closing. MPI is always optional.
What is the difference between mortgage protection insurance and term life insurance?
Both can cover a mortgage if the insured dies, but mortgage protection insurance is typically tied to one loan, often pays the lender or is earmarked for the balance, and frequently has a decreasing benefit with simplified underwriting. Term life pays a beneficiary you choose, keeps a level benefit for the term, usually involves fuller underwriting, and follows you to your next home. Features vary by policy, so read the contract.
Is mortgage protection insurance worth it?
It depends on your health, your existing coverage, your budget, and whether you want the benefit to pay off the house or go to your family. For someone who cannot qualify for traditionally underwritten coverage, a simplified-issue mortgage product may be the practical way to protect the home. For others, a broader policy may fit better. Review your own situation with a licensed insurance professional before deciding.
Is mortgage protection insurance the same as PMI?
No. PMI, private mortgage insurance, protects the lender if you default and is required on many conventional loans with less than 20% down. Mortgage protection insurance is an optional life insurance product that protects your household, not the lender.
How do I verify an insurance agent is licensed in New Jersey?
Ask for the agent’s full name and New Jersey producer license number, then check it through the New Jersey Department of Banking and Insurance licensing lookup. A legitimate agent will provide it readily.
The mortgage protection insurance NJ letters that pile up after closing are a marketing tactic built on public records, and nothing in them is required. But the underlying question they raise is a fair one: now that your family carries a Central Jersey mortgage, is the household protected if the person paying it is gone?
Mortgage protection insurance and term life insurance are two different ways to answer that, with real differences in who gets paid, whether the benefit shrinks, how much health underwriting is involved, and what happens when you refinance or move. Work through the five questions above, verify anyone you talk to, and make the decision in a conversation about your own situation rather than in response to a “final notice” from a company you have never met.
Just closed in Edison, Metuchen, or East Brunswick and sorting through the mail?
Text me a photo of any letter you are unsure about and I will tell you in plain English whether it is routine marketing. If you would like to review what coverage your family already has and what gaps a new mortgage creates, I hold both a New Jersey real estate license and an insurance producer license and am happy to walk through the questions in this article with you, in English, Mandarin, or Cantonese. No quotes by text, no pressure, just a conversation.
Jasmine Tsui (徐佳美)
Weichert, Realtors® | NJ Realtors® Circle of Excellence Platinum | Top 1% companywide
Central Jersey Realtor and Chinese Speaking Real Estate Agent, 16+ years in real estate, 200+ closed transactions, 220+ five-star reviews · Licensed NJ insurance producer
📍 123 Lincoln Hwy, North Edison, NJ 08820
📞 201-920-5825 · 🌐 NextMoveNJ.com
Serving Edison, Metuchen, East Brunswick, South Brunswick, Piscataway and across Middlesex County · Fluent in English, Mandarin (国语) and Cantonese (粤语)
NJ Real Estate License #2075070 · NJ Insurance Producer License #3000648745 · Equal Housing Opportunity
This article is general consumer education and is not insurance, financial, tax, or legal advice, and it does not recommend any specific policy, product, or carrier. Policy features, underwriting practices, and state rules vary and change over time; confirm current details with the insurer’s actual contract and with an appropriately licensed professional before making any decision. Real estate services provided through Weichert, Realtors®, 123 Lincoln Hwy, Edison, NJ 08820 · Equal Housing Opportunity. Insurance services offered separately through Premier Financial Alliance; Jasmine Tsui, NJ Insurance Producer License #3000648745. Links to government sites are provided for reference only.